Understanding APR Calculations in the UK
Thorough Examination of Loan Terms
When assessing various loan offers from UK lenders, it is crucial to conduct a thorough examination of the loan terms. This process entails a detailed analysis of interest rates, fees, and any promotional offers that may be applicable. By gaining a robust understanding of these elements, you can uncover the genuine cost of borrowing throughout the loan’s lifespan, which will empower you to make sound financial choices.
It is essential to bear in mind that some lenders may present enticing introductory rates that could change after a set period. Always account for the potential expenses across the entire loan duration rather than concentrating solely on the initial rate. This comprehensive approach will enable you to grasp your ultimate financial commitment more clearly.
Ensuring Adherence to Regulatory Standards
Ensuring adherence to regulatory standards is paramount when evaluating loan offers. It is vital to confirm that the lenders under consideration comply with the guidelines laid out by the Financial Conduct Authority (FCA). This regulatory organisation is dedicated to safeguarding consumers by fostering transparency and fairness in financial products across the UK.
When reviewing various offers, verifying that lenders conform to these standards is essential. This includes providing clear and accessible information regarding costs and associated risks. Such diligence not only protects your interests but also ensures access to dependable and trustworthy financial products.
How Do You Compare Representative Examples of APR?
When comparing APR across different loan offers, analysing representative examples can yield valuable insights into the performance of various loans in practical terms. Here are some significant advantages to consider for each loan type:
- Fixed-rate loans provide predictable monthly payments.
- Variable-rate loans might start with lower rates but can fluctuate over time.
- Secured loans generally offer lower rates due to collateral backing.
- Unsecured loans afford flexibility but may carry higher rates.
Each of these factors can have a considerable impact on your overall repayments. By scrutinising these examples, you can more effectively ascertain which loan type best aligns with your financial situation and goals.
Which Key Factors Influence APR Comparisons?
What Is the Role of Your Credit Score in APR Determination?
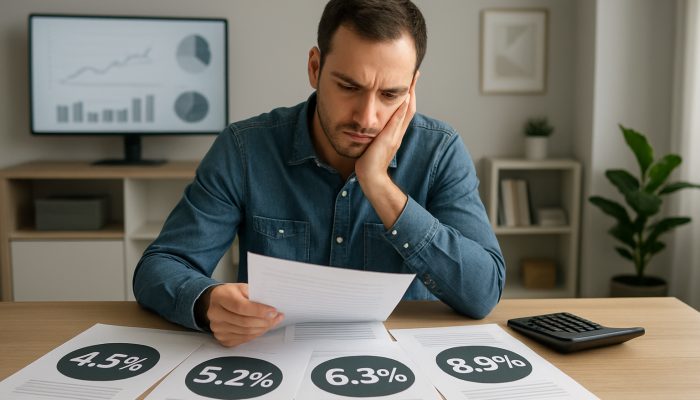
Your credit score plays a critical role in determining the APR offered by a variety of lenders. Typically, a higher credit score results in lower interest rates, as lenders perceive you as a less risky borrower. In contrast, individuals with lower scores may face higher rates or limited borrowing options.
By understanding your credit score and its implications for loan offers, you can make more informed borrowing decisions. Regularly reviewing your credit report helps you identify areas for improvement, potentially resulting in more favourable rates in future borrowing scenarios.
Why Is It Important to Assess Additional Charges and Fees?
Assessing additional charges is crucial when comparing APR across various loan offers. These may include arrangement fees, early repayment charges, and other costs that significantly affect the total expense of the loan. By factoring in these charges, you gain a clearer perspective of the actual cost associated with each credit agreement.
It is advisable to request a comprehensive breakdown of all potential fees from lenders. This level of transparency will empower you to compare offers effectively and make an informed decision that aligns with your financial needs.
How Do Repayment Periods Affect Loan Costs?
The repayment period of a loan can greatly influence both the APR and your monthly payments. Generally, longer repayment periods may result in lower monthly payments but can lead to a higher total interest paid over the loan’s duration. Conversely, shorter terms might entail higher monthly payments but lower overall interest costs.
When evaluating offers, consider how the repayment period corresponds with your financial objectives. Striking a balance between manageable monthly payments and total loan cost is essential for maintaining your financial well-being.
How Do Current Market Conditions Impact APR?
Current market conditions significantly influence the APRs available from various lenders. Economic trends, fluctuations in base interest rates, and competition among lenders can all affect the rates on offer. Staying informed about these developments can help you time your borrowing effectively.
For instance, during periods of economic uncertainty, lenders might raise rates due to perceived risks. Conversely, in a competitive market, lenders may reduce rates to attract borrowers. Understanding these dynamics enhances your ability to secure the most advantageous deal.
What Are the Key Borrower Eligibility Criteria?
Understanding borrower eligibility criteria is essential when comparing APRs. Lenders often establish specific requirements regarding income levels, employment stability, and credit history, all of which can influence the rates they offer. Familiarising yourself with these criteria enables you to assess which lenders are likely to present the most favourable terms.
Before applying for loans, it is wise to evaluate your financial situation and how it aligns with lender requirements. This preparation can save you time and allow you to focus on offers that suit your profile.
Effective Strategies for Comparing APR Across Offers
How to Utilise Real-World UK Banking Examples
Examining real-world examples from UK banking can provide valuable insights into uncovering hidden costs in credit card and personal loan offers. For example, a borrower may come across an attractive credit card with a low APR, only to discover significant fees for balance transfers or cash withdrawals that diminish the benefits.
Another common scenario involves personal loans that advertise low rates but are accompanied by high arrangement fees. By scrutinising these examples, borrowers can learn to look beyond the advertised rates and consider the total cost of borrowing, ensuring they make well-informed choices.
What Insights Can Expert Analysis Provide on Rate Variations?
Market conditions can lead to considerable differences in APRs between high street banks and online lenders. High street banks may provide stability and customer service but often charge higher rates due to their overhead costs. In contrast, online lenders typically offer competitive rates as they operate with lower overheads.
Understanding these distinctions empowers borrowers to select lenders that best meet their needs. An analysis of current market trends can help identify which lenders are likely to present the most advantageous rates based on your specific circumstances.
What Actionable Steps Can You Take for Verification?
To ensure you are making well-informed decisions, consider implementing actionable steps for verification. Contacting lenders directly can clarify any ambiguous terms or charges. Utilising official comparison tools approved for UK consumers can provide side-by-side assessments of multiple offers.
These tools often emphasise key differences in APR, fees, and terms, allowing you to make a more informed choice. Engaging with financial advisers can also provide personalised insights, ensuring you fully comprehend the implications of your loan choices.
Proven Tactics for Effectively Comparing APR Across Offers
Assessing Fixed Versus Variable Rates
Assessing fixed versus variable rates is a vital component of comparing loan offers. Fixed rates provide predictability, allowing borrowers to budget confidently. This can prove especially advantageous during periods of rising interest rates, as your payments remain stable.
On the other hand, variable rates may commence lower, appealing to those seeking immediate savings, but they carry the risk of fluctuating payments. Weighing the benefits and drawbacks of each option will aid you in determining the most suitable borrowing strategy for your financial situation.
How to Maximise the Use of Online Calculators
Maximising the use of online calculators can streamline the process of analysing loan rates. These tools enable you to input various loan amounts and terms, delivering instant comparisons of potential repayments and total costs. This can help you avoid overlooking compounding effects that could significantly alter your financial obligations.
By effectively utilising these calculators, you can make informed decisions based on accurate data. They can also illustrate the impact of different APRs on your overall repayment strategy, ensuring you choose the most advantageous offer.
Why Is Scrutinising Promotional Deals Essential?
Scrutinising promotional deals necessitates careful examination to avoid unexpected rate increases once the initial periods expire. Numerous lenders promote enticing introductory rates that revert to higher standard rates after a specified duration. It is crucial to understand the long-term implications of these offers.
Before finalising any decisions, calculate the total cost of the loan across its entire term, incorporating any potential rate increases. This diligence ensures you are not swayed by a temporary low rate that could result in higher payments in the future.
How Can You Avoid Common APR Pitfalls?
What Strategies Help in Identifying Misleading Advertisements?
Identifying misleading advertisements is vital to steering clear of seemingly attractive offers that may obscure essential fees. Many lenders in the UK promote low APRs without disclosing additional costs, such as arrangement fees or insurance that can significantly inflate the overall price.
Always read the fine print and inquire about any applicable fees. This vigilance can protect you from falling for offers that ultimately cost more than anticipated, ensuring you make informed borrowing decisions.
Why Should You Obtain Independent Financial Advice?
Obtaining independent financial advice from authorised advisers can clarify the complexities of navigating loan terms. These professionals offer insights tailored to your financial situation, helping you understand the implications of various offers and ensuring you select the most advantageous option.
Independent advisers possess extensive knowledge of the lending landscape and can assist you in avoiding common pitfalls. Their expertise can prove invaluable, particularly for first-time borrowers who may feel overwhelmed by the multitude of options available.
How to Keep Track of Annual Changes in the Lending Market?
Keeping track of annual changes in the lending market is essential for maintaining current comparisons. Economic fluctuations, such as modifications in the Bank of England’s base rate, can significantly impact the APRs offered by lenders. Staying informed about these alterations allows you to determine the optimal time to refinance or explore new credit options.
Regularly reviewing your financial situation alongside market conditions empowers you to make timely decisions. This proactive approach ensures you are consistently aware of the best available rates and products.
Why Is Comparing Multiple Lenders Crucial for Better Insights?
Comparing multiple lenders is vital for uncovering the true cost of credit. Each lender may present their APRs differently, often omitting significant fees. By investigating offers from various institutions, you can ensure a comprehensive understanding of what each loan entails.
Take the time to gather and compare detailed information from several lenders. This diligence will assist you in selecting the most favourable terms, ultimately saving you money over the loan’s lifetime.
How to Grasp Calculation Methods for APR?
Grasping the various calculation methods used to determine APR is essential for avoiding common pitfalls. Different lenders may employ distinct formulas, leading to variations in the APR quoted. Familiarising yourself with these methods allows for more accurate assessments of offers.
For instance, some lenders might include only specific fees in their APR calculations, while others may encompass all potential costs. Recognising these differences ensures you can make well-informed comparisons and select the best financial product for your needs.
How to Finalise Your Loan Decision with Confidence
How to Confirm Total Repayment Amounts Clearly?
Confirming total repayment amounts is crucial before signing any agreement with UK lenders. This step provides clarity on the complete cost of the loan, encompassing interest and any associated fees. Understanding your total financial commitment is essential for avoiding surprises in the future.
Request a detailed breakdown of repayments throughout the loan term. This transparency enables you to evaluate whether the loan aligns with your budget and financial goals, ensuring a more informed decision.
What to Look for When Scrutinising Contract Conditions?
Scrutinising contract conditions is a critical phase in the loan finalisation process. This involves carefully examining your obligations, including payment schedules, penalties for late payments, and options for early repayment. Understanding these terms can help you avoid potential pitfalls later on.
Pay particular attention to clauses regarding changes in interest rates or fees. Being aware of these conditions ensures you are fully informed about your commitments and can manage your finances effectively.
Why Consult Independent Financial Advisers?
Consulting independent financial advisers prior to committing to a loan can provide invaluable insights. Financial advisers can assist you in evaluating all available options in accordance with current UK financial regulations and your specific personal circumstances. This support ensures you make the most informed decision possible.
Engaging with a professional can also clarify complex loan terms and conditions, empowering you to navigate the lending landscape with confidence. Their expertise can help you identify the best products suited to your financial needs and objectives.
Commonly Asked Questions
What Does APR Stand For?
APR, or Annual Percentage Rate, represents the total cost of borrowing expressed as a percentage. It encompasses interest rates and any additional fees, providing a comprehensive overview of what a loan will cost over a year.
How Can I Improve My Credit Score Before Applying for a Loan?
You can improve your credit score by paying off outstanding debts, ensuring timely payments on bills, and checking your credit report for inaccuracies. Regular monitoring of your credit can also help maintain a healthy score.
Are There Different Types of APR?
Yes, there are various types of APR, including fixed APR, which remains constant throughout the loan term, and variable APR, which can change based on market conditions. Understanding these distinctions is vital for making informed borrowing decisions.
What Should I Consider When Reviewing Loan Terms?
When reviewing loan terms, consider interest rates, repayment periods, fees, and any promotional offers. Understanding these factors will help you evaluate the true cost of borrowing and avoid unexpected charges.
How Can I Effectively Compare Loan Offers?
To effectively compare loan offers, gather detailed information from multiple lenders, including APR, fees, and repayment terms. Utilise online comparison tools to assess these offers side by side for a clearer understanding of your options.
What Is a Representative APR?
A representative APR is the interest rate that at least 51% of borrowers will receive for a specific loan product. It serves as a benchmark, but individual rates may vary based on creditworthiness and other factors.
Can I Negotiate Loan Terms with My Lender?
Yes, you can negotiate loan terms with your lender. Discussing your financial situation and credit history may result in better rates or terms. It is worthwhile to ask if the lender can accommodate your needs.
What Are the Consequences of Missing a Loan Payment?
Missing a loan payment can lead to late fees, increased interest rates, and potential damage to your credit score. It is crucial to communicate with your lender if you anticipate difficulties in making payments.
How Often Should I Check My Credit Report?
You should check your credit report at least once a year to ensure accuracy and monitor your credit health. Regular reviews can help you identify areas for improvement and prevent potential issues when applying for loans.
What Are the Key Differences Between Secured and Unsecured Loans?
Secured loans require collateral, such as property or a savings account, which can lower interest rates. Unsecured loans do not require collateral but typically carry higher interest rates due to the increased risk for lenders.
Visit our Facebook profile for more insights!
This Article Was First Found On: https://www.debtconsolidationloans.co.uk